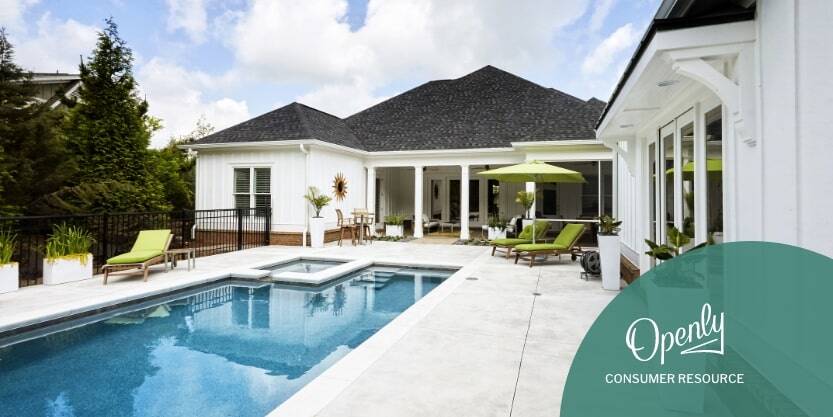
Homeowners insurance can cover a swimming pool, and carriers often set conditions before they write the policy, such as a fence with a self-latching gate. The pool itself can be covered for damage from fire, windstorm, vandalism, and other covered perils. Personal liability coverage pays when a guest is injured, and you are found legally responsible.
What are the insurance requirements for a swimming pool?
Carriers underwrite a pool as a liability exposure first, so most requirements limit unsupervised access to the water. Requirements differ by carrier and by town, and your agent confirms which apply before you apply.
| Requirement | What carriers may ask for |
|---|---|
|
Fence or barrier |
A fence around the pool with a self-closing, self-latching gate. Some carriers set a minimum fence height, and your town sets its own barrier rules. |
|
Door alarms |
Alarms on doors that open to the pool area when the house forms one side of the barrier. |
|
Diving boards and slides |
Some carriers may exclude them, charge more for them, or decline the pool. |
|
Pool condition |
A pool that holds water and stays in working repair. Some carriers may decline empty or damaged pools. |
|
Disclosure |
Tell your agent about the pool when you buy a home that has one and when you build one. An undisclosed pool risks a denied claim or a canceled policy. |
Each town defines a residential pool differently and sets its own fence, lock, and safety equipment rules. Call your municipality to learn the local standard.
Why might a pool raise your insurance risk and premium?
Having a swimming pool may be great when the weather's hot and you’re looking to cool off; but it’s important to understand how a pool affects home insurance. Swimming pools are considered high-risk features by insurance companies due to the increased potential for accidents and injuries.
- Increased liability—Children are especially vulnerable to drowning, even in shallower pools. Minor slips and falls around the pool area can also result in serious injuries. If a guest is injured and you are found legally responsible, your personal liability coverage will respond, and a pool raises the chance of that claim.
- Potential for property damage—Swimming pools are susceptible to damage from storms, freezing temperatures, or falling trees. Repairs for these issues can be costly.
Homeowners with a pool typically pay more than they would without one. The size of the increase can depend on the pool type (in-ground or above-ground), the replacement cost of the pool, the fence and other safety features, the liability limit you choose, and your claims history.
What does homeowners insurance cover for a swimming pool?
A homeowners insurance policy can pay for pool damage from a covered peril, such as fire damage, windstorm, or vandalism, up to the limit of the coverage part that applies and minus your deductible. Where your policy places the pool varies by carrier and pool type.
In general, in-ground pools are typically covered under other structures coverage, while above-ground pools may be covered under either other structures or personal property coverage. Check with your insurer to understand how your policy covers your pool and discuss any additional coverage you might need.
Liability coverage
Personal liability coverage pays medical bills, lost wages, and legal defense costs if a guest is injured in or around your pool and you are found legally responsible, up to your policy limit. Medical payments to others coverage pays a guest’s smaller medical bills whether or not you are at fault. Neither coverage pays for injuries to you or members of your household.
Personal property coverage
Personal property coverage pays for portable pool equipment and accessories, such as pool covers, vacuums, heaters, and pool furniture. Carriers treat built-in equipment, including pumps, filters, and diving boards, as part of the pool structure.
What does homeowners insurance not cover with a pool?
A homeowners policy may exclude pool damage that comes from age, neglect, or a peril the policy does not cover. These exclusions typically apply to pool claims on a standard policy:
- High-risk features—Some insurers may not cover pools with diving boards or slides due to the higher risk of serious injuries. If they do cover high-risk features, you may see a higher premium.
- Liability—While liability coverage can help if someone is hurt in your pool, it may not apply if the accident was due to owner negligence or failure to maintain proper safety measures, leaving you on the hook for damages.
- Wear-and-tear—A liner that fails from age or a surface that cracks from years of use is a maintenance cost, not a claim.
- Lack of maintenance—A pump that burns out because debris clogged the filter is not covered.
- Skipped winterizing—In freezing climates, cracks and leaks that follow a failure to lower the water level and drain the equipment are not covered.
- Coverage caps—There may be limitations on the amount your insurance covers for pool-related claims. This could be a specific dollar amount or a percentage of your dwelling coverage.
Which safety measures reduce pool risk?
Safety measures lower the chance of an injury claim, and some lower your premium. Ask your agent which measures your carrier credits.
- Pool fencing—Having a secure fence with a self-closing and self-latching gate around the pool perimeter is a condition carriers attach to pool coverage and a barrier rule in many towns. A well-maintained fence blocks unsupervised access, especially by young children and pets.
- Pool alarms—A gate alarm sounds when someone opens the pool gate, and a surface or underwater alarm detects movement in the water.
- Pool covers—A safety cover rated to hold a person’s weight keeps the water out of reach when the pool is closed.
- Regular pool maintenance—A well-maintained pool with balanced chemicals and proper circulation is less likely to experience leaks or accidents. In addition, repairing chipped tiles or other potentially dangerous damage can show the insurance company you are a responsible pool owner.
- Lighting and a clear deck—Light the pool area at night and keep the deck free of glass, toys, and clutter.
- Supervision and rules—Post pool rules, keep a reach pole and a first aid kit at the pool, and have an adult trained in CPR watch the water whenever anyone is swimming.
- Photo documentation—Photograph the fence, gate, alarms, and signs. The photos show your safety measures were in place if you file a claim.
These are just some examples, and it's always best to check with your specific home insurance provider to see how they view different safety measures and ways to reduce your home insurance premium.
How do you confirm your pool is covered?
Walk through these five steps with your independent agent when you buy a home with a pool, add a pool, or renew your policy:
- Disclose the pool. Give your agent the pool type, the fence and gate details, and any diving board or slide.
- Ask which coverage part pays for the pool and what the limit is.
- Inventory your pool equipment. List the pump, filter, cleaner, cover, and heater with photos and receipts, so a covered claim moves faster.
- Review your liability limit and ask whether an umbrella policy fits your assets and pool exposure.
- Report changes at renewal, such as a new fence, heater, deck, diving board, or cover.
How do you find home insurance for a home with a pool?
Openly is a home insurance provider that sells exclusively through independent insurance agents, who compare coverage and confirm pool eligibility for your home. If you already work with an independent agent, ask whether Openly is available for your home. If you do not, use Openly’s Find an Agent page to locate home insurance agents near you who are appointed with Openly, and ask for a quote for home insurance.
Tell your agent about the pool before the application, not after the claim.
* We provide this information to help you understand insurance. Any coverage is subject to the terms of your policy. Please refer to your policy and declarations page for complete terms, conditions and coverage details.
1 Les Masterson. “Does homeowners insurance cover swimming pools?.” Insurance.com Published 20 May 2024. Accessed 13 June 2024. https://www.insurance.com/home-and-renters-insurance/coverage/new-pool-your-homeowners-policy.aspx
2 Insurance Information Institute. “Pool Safety & Insurance.” III.org. Accessed 13 June 2024. https://www.iii.org/article/pool-safety-and-insurance